France's Rising Debt Costs Threaten Stability Amid Protests
France's plans to increase education spending are jeopardized by its soaring public debt and rising interest costs, threatening the nation's financial stability.
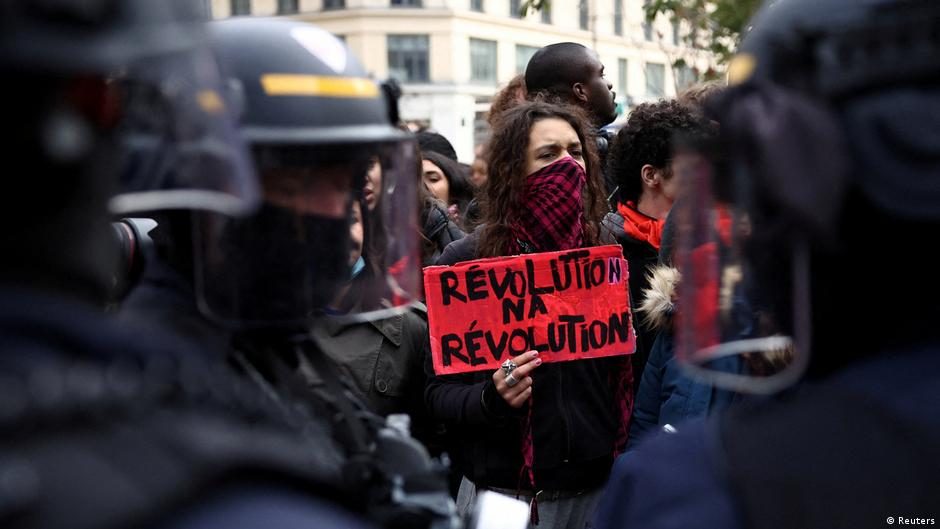
France is planning to allocate an additional €4 billion to education amidst ongoing nationwide protests. However, the country's public debt, which stands at approximately 120% of its GDP, coupled with rapidly increasing interest costs, severely limits the government's fiscal capacity. This situation, combined with political instability, makes France's financial outlook increasingly precarious.
Highlights
- France aims to provide €4 billion in low-interest loans for school renovations and an additional €1 billion for universities.
- The nation's public debt is roughly 120% of its Gross Domestic Product (GDP).
- France's credit rating ranges from AA to Aa3, with a negative outlook from several agencies, in contrast to Germany's stable AAA rating.
- The French government pays nearly 1.6 percentage points more in interest than Germany on 10-year bonds.
- Interest payments are projected to exceed €79 billion in 2026, potentially reaching €125-132 billion by 2030.
Details
France's substantial public debt and political polarization are exacerbating its financial challenges. The government's lack of a parliamentary majority further complicates the situation. Economist Friedrich Heinemann from the Leibniz Center for European Economic Research notes that the risk premium (spread) between German and French government bonds has reached its highest level since the financial crisis. This increases France's borrowing costs, potentially putting pressure on banks and the broader economy.
Landry Charrier, a researcher at the University of Bonn, suggests that the French public perceives high debt as an abstract concept, with 56% of the population receiving more in government benefits than they pay in taxes. This creates a strong public interest in maintaining the status quo. For over half a century, France has consistently spent more than its tax revenues, last balancing its budget in 1974.
Rising interest costs mean a larger portion of the national budget must be allocated solely to debt servicing. Interest payments, expected to surpass €79 billion in 2026, could climb to between €125 billion and €132 billion by 2030. These figures include costs incurred by social security funds and local authorities. In the coming years, France will need to refinance significant amounts of bonds issued during periods of historically low interest rates, while its substantial budget deficit necessitates taking on additional debt.
Why it matters
France's escalating debt costs not only threaten its own financial stability but also could impact the overall economic health of the European Union. Experts warn of the potential for a financial crisis. Costly promises from political parties and the public's perceived lack of understanding of the debt's severity could lead to the postponement of necessary fiscal adjustments, creating larger problems in the long run. The Euro's provision of cheap financing has suppressed the warning signals that currency devaluations once provided, fostering an illusion that necessary adjustments can be indefinitely delayed.